What Is ROE? Step-by-Step Calculation and Screening Guide
Fundai Education Team · · 8 min read
From calculating return on equity with a hypothetical example to comparing against the industry and building a filter in Fundai, learn the uses and limitations of ROE step by step.
The answer to the question "what is ROE" is this: return on equity is the ratio of net profit to shareholders' equity, and in Fundai its trailing twelve-month version is calculated using the net profit of the last four quarters. To interpret the ratio, you need to look at the time basis of the profit, the size of shareholders' equity and the company's debts together. We follow a hypothetical example from the calculation through to building a filter condition; the figures in the example are not real data for any listed company.
Step 1: What is ROE, and which version should you read?
In Fundai, ROE TTM equals net profit for the most recent twelve months divided by total equity on the latest balance sheet, and it is shown as a percentage. To rebuild the ratio, record both the profit period and the balance sheet date; the profit belongs to a period, whereas the balance sheet shows the company's position on a single date.
For a practical answer to the question "what is ROE", first identify the time basis of the figure. Periodic ROE uses the profit of the reported period and is not annualized; therefore, comparing it directly with the twelve-month version is not valid.
Read the ratio name and time basis In the "Financial ratios" section of the company page in Fundai, identify whether you are reading the twelve-month version or the periodic one. To learn about the sections of the company page, use the Fundai user guide.
Check the profit period Interim reports on the Codal system are cumulative; do not add the three-month, six-month and nine-month profits together as profits of separate quarters. TTM profit is the sum of the net profit of the last four reported quarters, not necessarily the profit of the latest fiscal year.
Match the denominator definition If another source has used average equity, the result may differ from Fundai's figure. To rebuild our figure, use total equity on the latest balance sheet.
Step 2: Where in the financial statements do you find the items of the ROE formula?
Take net profit from the income statement and total equity from the latest statement of financial position. On the company page in Fundai, open the "Income Statement" and "Balance Sheet" reports; we display the items the company has published in these reports.
Gross profit, operating profit and earnings per share are not substitutes for net profit. To identify the right lines, see our guide to reading the income statement. On the balance sheet, likewise, take total equity, not just registered capital or retained earnings.
Check the statement title, the reporting period, the balance sheet date, and whether the statements are separate or consolidated. Net profit and equity must belong to the same company and the same reporting scope; do not combine consolidated profit with separate-company equity. Also make sure the display unit of the two figures is the same.
Twelve-month return on equity, in percent
Equity, billion tomans
Twelve-month return on equity, percent
Twelve-month return on assets, percent
Based on the figures of this article's hypothetical example, ROE is 20%; that is, twelve-month net profit equals this share of equity on the latest balance sheet. Return on assets has also been calculated with the same hypothetical profit; in the next step, examine the difference between the denominators of the two ratios.
Step 3: Why a higher ROE is not enough without checking ROA and debt
ROE measures net profit against shareholders' equity, while ROA compares the same profit with total assets. In the financial ratios section, read ROA TTM and the debt-to-assets ratio alongside ROE TTM so that you also examine the size of the denominators and the financial structure.
| Ratio | Numerator | Denominator | Analytical question |
|---|---|---|---|
| ROE TTM | Twelve-month net profit | Total shareholders' equity in the latest balance sheet | How large is net profit relative to shareholders' equity? |
| ROA TTM | Twelve-month net profit | Total assets in the latest balance sheet | How large is net profit relative to total assets? |
| Debt-to-assets ratio | Total liabilities | Total assets on the same date | What share of assets is financed by debt? |
Assuming net profit and assets stay constant, smaller shareholders' equity can make ROE look higher. Such a change alone does not prove an increase in earning power; the numerator has stayed the same and only the denominator has changed.
Total liabilities are not just loans; they also include trade and non-trade payables, taxes and dividends payable, advances received, provisions and financial facilities. The total liabilities figure does not allow you to infer the cost of financing; examine finance costs in the income statement.
To examine financial leverage, look at the size of liabilities and shareholders' equity alongside net profit. A high ROE together with high debt does not by itself show that debt was the cause of the level of profit or of the ratio; explaining the cause requires more evidence from the company's reports.
With very small shareholders' equity, ROE becomes sensitive to changes in the denominator; with a zero denominator, the ratio cannot be calculated. If shareholders' equity is negative, check the sign of profit separately: dividing a loss by negative shareholders' equity also gives a positive result. Therefore, ranking by ROE alone may place a loss-making company in a positive output as well.
Step 4: What ROE Figure Is Appropriate on the Iranian Stock Market?
Without specifying the industry, the time basis, the financial structure and the components of profit, a single ROE figure is not enough to form a judgment. Instead of setting a general threshold, define the comparison group. In addition to industry peers, measure ROE against the risk-free rate, for example the yield on government bonds, and against the inflation rate: a return on equity below both of these does not cover the opportunity cost of the shareholder's money.
Select peer companies in the same industry and check their earnings periods and balance sheet dates. If the companies' latest reports belong to different times, take the time gap into account when interpreting the differences in the ratios. Also make sure the comparison is made on the same basis, that is, period against period or TTM against TTM.
In the "Financial Ratios" section of a company's page on Fundai, we show the company's ratio next to the figure for the whole industry and the market. The whole-industry ratio is obtained by dividing the total twelve-month net profit of the industry's companies by their total equity; it is not the simple average of the companies' ROE. A gap from the aggregate industry figure is not, on its own, a verdict that the company is superior.
According to the Board of Directors' activity report of Saroj Bushehr, the return on shareholders' equity of the symbol SAROJ has been reported for fiscal year 1402. According to the management's interpretive report of Iran Refractories Products on Rahavard 365, the same ratio has also been reported for the symbol KAFARA for fiscal year 1402. Before comparing the reported ratios with Fundai's, check the earnings period and the definition of the denominator in each source; the same name for a ratio does not prove that the calculation is the same.
To complete the review, read the composition of the revenues and expenses affecting net profit in the income statement, and examine operating cash flow in the cash flow statement. If the difference between accounting profit and cash flow is new to you, use the guide to reading financial statements. The conclusion should be an explanation of the components of profit and the cash position, not a label of earnings quality based solely on ROE.
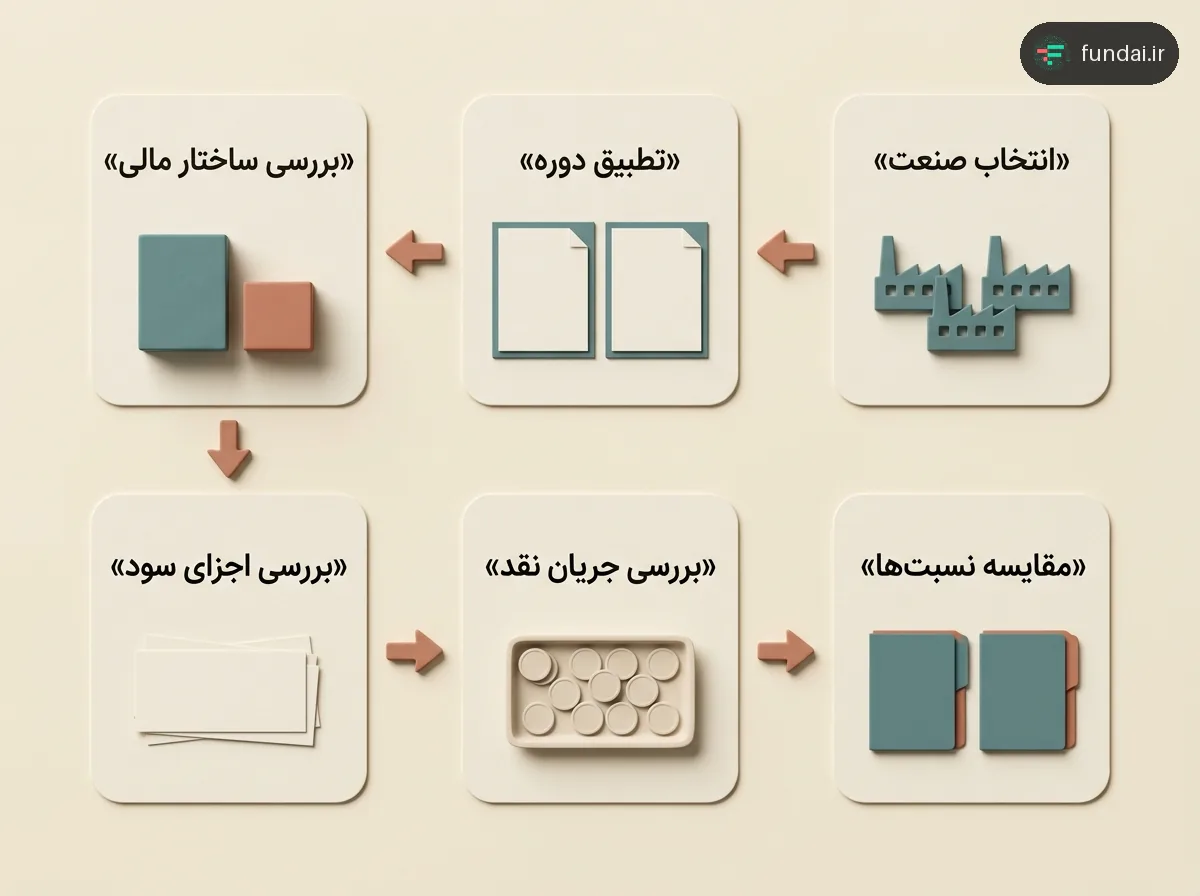
Step 5: Summary — How do you turn ROE into a filter you can review?
The ROE filter builds a checklist; to interpret the output, trace the numeric condition back to each company's net profit and balance sheet. In Fundai, select one of the output symbols and check the basis of the ratio in its financial statements. Past data does not guarantee the future. The result of your review should be a documented explanation of the basis of calculation and the limitations of the comparison, not just a symbol ranking.
Define the scope of the review On the filters page, select the industry you want under "General filters". A defined scope limits the comparison of the output to companies in that industry.
Build the educational condition From the "Financial ratios" family, select the variable ROE TTM. To continue the hypothetical example, set the operator to "greater than or equal to" and the value to 20; the selected threshold is simply the result of the example, not a general measure of company quality.
Open one output symbol In the financial ratios section, read ROE alongside ROA, the debt-to-assets ratio and the industry-wide ratio. Then check the sign of net profit and of shareholders' equity in the financial statements so that you do not mistake a positive ratio for profitability.
Document the result Record the earnings period, the balance sheet date, and whether the figures are separate or consolidated. Determine whether the result is due to the size of the profit or the smallness of shareholders' equity; if the evidence is insufficient, write the cause as undetermined.
What is ROE and how is it calculated in Fundai?
ROE, or return on equity, is the ratio of net profit to total shareholders' equity. In Fundai, the twelve-month version uses the net profit of the last four reported quarters and the total shareholders' equity from the latest balance sheet, and is displayed as a percentage.
Is a higher ROE always a sign of better company performance?
A higher ROE alone does not prove better performance; smaller shareholders' equity can also increase the ratio. To interpret it, review net profit, the size of shareholders' equity, ROA and debts on the same time basis.
Does a positive ROE always mean the company is profitable?
A positive ROE does not always mean profitability. If net profit and shareholders' equity are both negative, the result of the division is positive; therefore, check the sign of each figure separately in the financial statements.
#Fundamental Analysis Education #Return on Equity #Stock Screener #Financial Ratios